I love these foodie VAT cases that come along every now and again – Jaffa Cakes, Tunnocks Tea Cakes and Milkshake flavours to name a few – they are a great reminder of the intricacies of our VAT legislation and how this is adapting to our changing appetites!
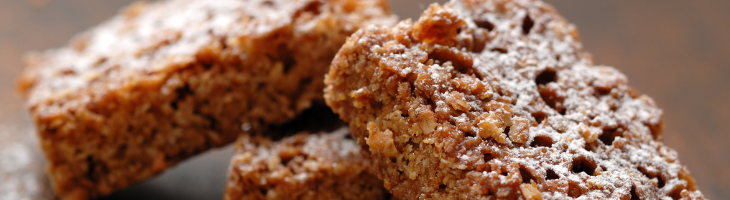
Now we have another one to add to the list – flapjacks. Historically, they have always been classed as cakes for VAT purposes – and therefore zero-rated – and at the time of writing, HMRC’s VAT manuals still include flapjacks at the top of their list of products which are zero-rated as cakes.
Glanbia Milk Limited duly zero-rated a number of their products, which they described as flapjacks. HMRC considered that the products were not flapjacks (cakes) but cereal bars (classed as sweets) and raised an assessment for underpaid VAT on the grounds that these products should have been standard-rated.
The case was heard by the First Tier Tax Tribunal (FTT) in April 2022, and went in favour of HMRC. The FTT didn’t consider whether these particular products were flapjacks or not, only whether they were cakes, and decided that they weren’t for a number of reasons, including:
- They were not products that people would normally eat for afternoon tea
- They were not baked
- Their main ingredients were oats, syrup and protein
- Their texture and appearance were not typical of cakes
- The products were promoted in the specialist nutrition sector with emphasis on their high protein content – not the image normally associated with cakes
So, when is a flapjack not a flapjack? When it is a cereal bar.
HMRC’s manual sets out how their views have changed as traditional flapjacks have developed over the years and become more varied.
When VAT was first introduced in 1973 flapjacks were just made of oats, and generally perceived as cakes which could be baked at home.
While HMRC will accept that minor variations such as adding dried fruit, chocolate chips or a yogurt topping doesn’t change their zero-rated cakey status, adding other cereals is a step too far. Add too many and a flapjack becomes a cereal bar, and once this happens then for VAT purposes it stops being a zero-rated cake and becomes standard-rated confectionary.
For anyone who would like to read more, click here.